
Private Credit Investing: Risks Beyond the Headline Yield
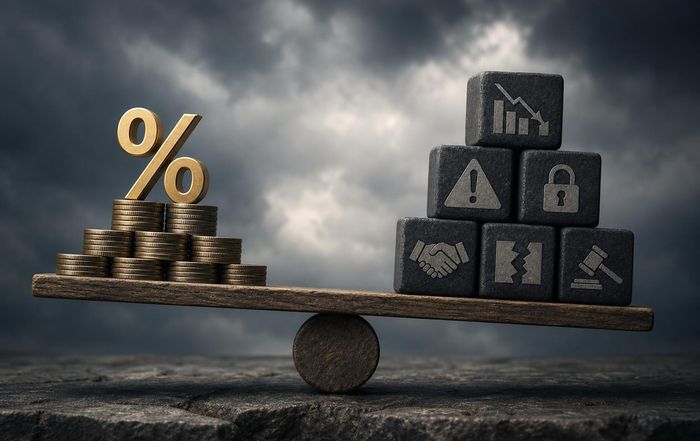
Private credit has moved from a niche asset class to a central pillar of global markets. With policy rates still relatively high in many economies and banks more cautious after recent turmoil, direct lending and other forms of private credit promise something investors crave: high, contractual yields that seem insulated from daily market volatility. Yet the very features that make private credit attractive-illiquidity, bespoke structures, and lighter regulation-also create risks that are easy to underestimate when attention is fixed on double-digit coupons.
Today we examine what sits behind those eye-catching yields, where the main risks lie, how they differ from traditional fixed income, and what institutional and sophisticated individual investors should probe before allocating capital.
How private credit grew so quickly-and why that matters for risk
Private credit broadly refers to non-bank lending that is not financed or traded through public markets. It includes direct lending to mid-market companies, mezzanine finance, asset-backed lending, specialty finance (such as litigation or royalty financing), distressed debt, and opportunistic credit strategies. According to estimates from Preqin and PitchBook, assets in private debt funds have grown from under $500 billion a little over a decade ago to well over $1.5 trillion today, with some forecasts projecting the market could approach $3 trillion later this decade.
Several structural forces explain that expansion. Post-2008 banking regulation such as Basel III pushed banks to hold more capital against riskier loans, encouraging them to retrench from certain corporate and leveraged lending activities. At the same time, institutional investors faced a long period of low yields on government and investment-grade bonds, making the illiquidity premium of private credit look compelling. Private equity sponsors also preferred bespoke, speedy financing from direct lenders over lengthy syndicated bank processes. These shifts created an ecosystem in which private credit funds, often backed by large alternative asset managers like Blackstone, KKR, Apollo, and Ares, stepped into roles historically filled by banks.
That structural context matters because it shapes the risk profile. Private lenders often deal with more leveraged borrowers, more concentrated portfolios, and weaker covenants than traditional bank lending. Meanwhile, the rapid inflow of capital has at times compressed spreads and encouraged more aggressive structures, especially in competitive sponsor-backed deals. For investors reading a fund's marketing deck, this means headline yields may not fully reflect the underlying credit quality, structural protections, or potential loss severity in a downturn.
Readers interested in broader credit and capital-market dynamics can find complementary coverage in our markets and economy sections.
Headline yield vs. real risk-adjusted return
The central promise of private credit is a higher yield than public bonds of similar credit risk, often framed as an "illiquidity premium." In practice, several factors complicate that narrative.
First, yields are typically quoted on a gross basis, before fund-level management and performance fees, which in private markets can be substantial. A direct lending fund offering a 10-12% gross yield may deliver materially less on a net basis after fees, reserves, and potential write-downs. Second, yield alone does not capture expected loss: a portfolio of loans with a 12% coupon but a 5% annual default rate and high loss severity can produce a worse risk-adjusted outcome than a lower-yielding but safer portfolio.
Third, private credit returns are usually reported with low volatility because loans are marked to model rather than to market. This can create an illusion of stability. Public high-yield bonds or leveraged loans repriced daily by the market will exhibit higher mark-to-market volatility even if their long-term credit risk is similar. For asset allocators, this can make private credit look unusually attractive on Sharpe ratio or risk-adjusted metrics, but part of that effect reflects valuation methodology rather than truly lower risk.
Regulators such as the Bank for International Settlements at https://www.bis.org/ and central banks like the Federal Reserve at https://www.federalreserve.gov/ have increasingly highlighted this "hidden leverage" and opacity as areas to watch. Investors need to distinguish between accounting smoothness and economic resilience.
Credit risk in a higher-for-longer rate environment
At its core, private credit is still credit: the risk that borrowers cannot or will not repay their obligations. Many private loans are floating rate, often priced as a spread over benchmarks such as SOFR, Euribor, or other reference rates. When rates rise, investors benefit from higher coupons-but only as long as borrowers can absorb the increased interest burden.
After the rapid rate hikes led by central banks like the European Central Bank at https://www.ecb.europa.eu/ and the Bank of England at https://www.bankofengland.co.uk/, interest coverage ratios across leveraged borrowers have come under pressure. Companies that refinanced cheaply in the late 2010s now face much higher all-in yields on new or floating-rate debt. Sectors with cyclical revenues, low pricing power, or high input-cost sensitivity are particularly vulnerable.
Private credit funds often highlight low historical default rates, but much of the modern direct-lending boom occurred in an environment of falling or low interest rates and abundant liquidity. The real test is how these portfolios perform through a full credit cycle marked by sustained higher rates, slower growth, and potential recession in key economies. Default rates in public leveraged loans and high-yield bonds, tracked by rating agencies such as Moody's at https://www.moodys.com/ and S&P Global Ratings at https://www.spglobal.com/, can provide a rough reference point, but private credit exposures may differ in sector mix, leverage, and covenant protection.
For investors tracking broader corporate debt and employment implications, our business and employment pages regularly explore how financing conditions feed through to hiring, investment, and growth.
Covenant erosion and weaker lender protections
A defining feature of many private loans today is the gradual erosion of traditional lender protections. "Covenant-lite" structures, popularised in the syndicated leveraged loan market, have spread into parts of private credit. Instead of maintenance covenants that test leverage or interest coverage regularly and allow lenders to intervene early, many deals rely on incurrence covenants or looser tests that only trigger when the borrower takes specific actions such as incurring additional debt.
For investors, weaker covenants mean fewer early-warning signals and less ability to renegotiate or enforce remedies before a borrower's situation deteriorates sharply. Recovery rates in distressed situations can be significantly lower when lenders lack strong security packages, guarantees, or financial maintenance tests. Legal complexity further complicates matters: large sponsor-backed borrowers often have multi-layered capital structures and sophisticated advisers, making restructurings time-consuming and costly.
Supervisory bodies like the European Securities and Markets Authority (ESMA) at https://www.esma.europa.eu/ and national regulators have cautioned about aggressive documentation in leveraged finance, though much of private credit sits outside the most direct regulatory perimeter. This increases the onus on limited partners (LPs) to scrutinise a manager's underwriting discipline, covenant standards, and historical workout experience rather than assuming that all "senior secured" labels provide equal protection.
Illiquidity, valuation opacity, and timing risk
Illiquidity is often framed as a feature, not a bug: in exchange for locking up capital for seven to ten years, investors are told they earn an illiquidity premium. However, illiquidity is a double-edged sword. It restricts an investor's ability to rebalance portfolios, meet unexpected cash needs, or exit underperforming strategies. In stressed scenarios, secondary markets for private credit fund interests can be thin, with discounts to net asset value (NAV) that may widen sharply.
Valuation opacity compounds this risk. Unlike public bonds priced continuously on exchanges or dealer quotes, private loans are typically valued using models, comparable transactions, or manager judgments. Independent valuation agents and auditors provide some oversight, but there is no daily market check. During benign periods this can smooth returns; during downturns it raises questions about how quickly and accurately impairments are recognised.
For multi-asset allocators, this timing mismatch can be problematic. Public market assets may sell off rapidly in a downturn, while private credit valuations adjust more slowly. That can distort portfolio-level risk metrics and lead to overallocation to illiquid assets, sometimes called the "denominator effect." Institutions such as Mercer at https://www.mercer.com/ and Cambridge Associates at https://www.cambridgeassociates.com/ have written extensively about pacing models and liquidity budgeting to manage these dynamics, but implementation still requires discipline.
Readers considering portfolio construction across private and public markets may also find our investment and markets coverage useful.
Concentration, manager dispersion, and operational risk
Unlike broad public bond indices, many private credit funds run relatively concentrated portfolios. A mid-market direct lending fund may hold a few dozen core positions; a specialty finance strategy might be even more focused. This concentration can amplify idiosyncratic risk: a single problematic borrower or sector can materially drag on fund-level performance.
Manager dispersion is another underappreciated risk. Research from organisations like Preqin at https://www.preqin.com/ and PitchBook at https://pitchbook.com/ shows that top-quartile private debt funds can significantly outperform median or bottom-quartile peers over a fund's life. However, past performance is an imperfect guide, particularly for firms that have grown assets rapidly or expanded into new strategies. Key-person risk also looms large: underwriting quality often depends on a small group of experienced professionals, and turnover or team splits can affect consistency.
Operational and legal risks should not be overlooked. Complex fund structures, use of leverage at the fund or vehicle level, and reliance on subscription credit lines or asset-backed facilities can all introduce additional layers of risk beyond the underlying loans. Institutional investors increasingly scrutinise governance, risk management, and alignment of interest, including GP commitment and fee structures. Industry bodies such as the Institutional Limited Partners Association (ILPA) at https://ilpa.org/ provide guidelines and due-diligence frameworks that can help LPs interrogate these issues.
Systemic and macro-financial considerations
From a macro-financial perspective, the growth of private credit raises questions that go beyond individual portfolios. Supervisors at the International Monetary Fund (IMF) at https://www.imf.org/ and the Financial Stability Board (FSB) at https://www.fsb.org/ have highlighted the broader "non-bank financial intermediation" (NBFI) sector as a potential source of systemic risk. While private credit funds are generally less leveraged than banks and do not offer deposit-like liabilities, their interconnectedness with other financial institutions, including banks that provide fund-level leverage or credit facilities, creates potential transmission channels.
One concern is that in a severe downturn, widespread stress across private credit portfolios could lead to simultaneous valuation hits, constraints on new lending, and difficult restructurings for sponsor-backed companies that employ large numbers of people. This could amplify economic slowdowns, particularly in economies where private credit plays a significant role in financing mid-sized businesses. Another concern is transparency: because private credit markets are less visible than public bond markets, policymakers may have a less complete picture of where risks are concentrated.
For business owners and founders, the implications are two-sided. On the one hand, private credit provides flexible financing options when banks pull back, supporting investment and growth. On the other hand, reliance on a small number of private lenders can create refinancing and negotiating vulnerabilities in times of stress. Entrepreneurs exploring financing options can find related perspectives in our founders and banking sections.
Due-diligence questions sophisticated investors should ask
For institutions, family offices, and high-net-worth investors evaluating private credit allocations, a more forensic approach is essential. Rather than focusing primarily on target net IRRs or yield ranges, LPs increasingly probe several areas.
They examine underwriting standards and covenant discipline, asking managers to provide anonymised examples of recent deals, including leverage levels, security packages, and covenants. They assess sector exposures and scenario analyses, exploring how portfolios might behave under stress cases such as a recession, a spike in defaults, or a prolonged "higher for longer" rate environment. They scrutinise how managers have handled past restructurings, including recovery rates and time to resolution, and whether the firm has dedicated workout teams.
Liquidity management is another focal point: investors ask about the use of fund-level leverage, subscription lines, and any redemption or distribution-in-kind mechanisms. They also drill into valuation governance, including who sets marks, how often they are reviewed, and how conservative assumptions are in stressed situations. Finally, alignment of interest-fee structures, hurdle rates, GP commitment, and co-investment opportunities-remains central to ensuring that managers are incentivised to protect downside, not just grow assets under management.
Frameworks and thought leadership from organisations like CFA Institute at https://www.cfainstitute.org/ and consulting firms such as McKinsey & Company at https://www.mckinsey.com/ and Bain & Company at https://www.bain.com/ can provide additional context for building robust due-diligence processes.
Where private credit can still make sense
None of this means investors should avoid private credit altogether. For many diversified portfolios, it can play a constructive role, especially when approached with realistic expectations and rigorous manager selection. Certain niches-such as conservative senior secured lending to resilient sectors, asset-backed strategies with strong collateral, or specialised financing where managers have genuine domain expertise-may offer attractive risk-adjusted returns relative to public markets.
The key is understanding that the extra yield is compensation for a bundle of risks: illiquidity, complexity, opacity, and credit exposure that may be more cyclical than recent performance suggests. Investors who treat private credit as a "bond substitute" without fully accounting for these differences risk being surprised when the credit cycle turns. Those who approach it as a higher-risk, higher-complexity strategy within a broader alternatives allocation, and who build in appropriate liquidity and diversification safeguards, are better placed to capture its potential benefits without being blindsided by the less visible hazards behind the headline yield.
For ongoing key coverage of credit markets, private capital, and how financing trends affect companies and jobs worldwide, readers can explore our news, world, and technology pages, where evolving data, regulation, and market structure are tracked as they develop.