
Why Productivity Growth Matters More Than Output Alone
When economies are booming, headlines tend to focus on big numbers: record GDP, soaring factory output, surging exports. Yet for long-term prosperity, what matters more than how much we produce is how efficiently we produce it. That efficiency-productivity-is the quiet force behind rising wages, higher living standards, stronger profits, and sustainable public finances. Understanding why productivity growth matters more than output alone is critical for business leaders, policymakers, investors, and workers trying to make sense of a world where growth is slowing in many advanced economies despite impressive technological change.
What economists really mean by "productivity"
In everyday language, productivity often means "working harder" or "doing more in less time." Economists use the term more precisely. At its core, productivity measures how much output is produced for each unit of input. The most common measure, labor productivity, is typically defined as output per worker or per hour worked. A related concept, total factor productivity (TFP), looks at how efficiently all inputs-labor, capital, and sometimes energy and materials-are transformed into output.
Institutions such as the Organisation for Economic Co-operation and Development (OECD) and the U.S. Bureau of Labor Statistics (BLS) track these metrics across countries and industries. When labor productivity rises, it means that, on average, each hour of work is producing more goods or services. That can happen because of better technology, improved skills, smarter management, more efficient processes, or better organization of capital and infrastructure.
This distinction matters because an economy can increase total output simply by adding more workers or extending working hours, without becoming any more efficient. That kind of growth is inherently limited. Populations age, labor participation plateaus, and there are only so many hours people can work. By contrast, productivity growth allows output to rise even when the number of workers or hours stays the same-or even falls. For countries facing demographic headwinds, such as Japan or much of Europe, productivity is not just desirable; it is essential.
For readers interested in how productivity links to broader business performance and macro trends, the lens of productivity is closely connected to themes we cover under business and management, economy, and employment across global markets.
Why productivity is the engine of rising living standards
Over long periods, sustained improvements in living standards are almost entirely driven by productivity growth rather than by simple increases in output. Research from institutions such as the World Bank (worldbank.org) and International Monetary Fund (imf.org) consistently shows that countries with higher productivity levels and stronger productivity growth tend to have higher incomes per capita, better health outcomes, and more fiscal capacity to invest in education, infrastructure, and social safety nets.
The mechanism is straightforward. When workers produce more value per hour, firms can afford to pay higher wages without necessarily increasing prices or sacrificing profitability. Higher wages, in turn, support greater consumption and savings, which can finance investment in new capital and innovation. Governments benefit from higher taxable income and corporate profits, which expand the fiscal room to fund public goods and social programs without unsustainable borrowing.
Historically, the post-war economic booms in the United States, Western Europe, and parts of East Asia were underpinned by rapid productivity gains alongside capital deepening and trade integration. Studies by organizations such as McKinsey Global Institute (mckinsey.com) and the OECD have highlighted that sectors with strong productivity growth-manufacturing, information and communications technology, logistics, and some business services-often contribute disproportionately to overall GDP growth and wage gains.
By contrast, when productivity stagnates, economies can still grow for a time by adding more workers or leveraging credit-fuelled demand, but this often leads to imbalances. Wage growth lags, inequality may widen, and governments find it harder to fund pensions and healthcare as populations age. Many advanced economies have experienced precisely this pattern since the mid-2000s: modest GDP growth, low wage growth for median workers, and rising public debt.
For businesses and investors, this dynamic is central to strategic planning. Firms operating in high-productivity sectors or regions often enjoy better margins and more room to invest in innovation. That is why productivity is not just a macroeconomic curiosity; it is a core driver of value creation and risk across markets and investment decisions.
The limits of chasing output for its own sake
Focusing on output alone can be misleading and even dangerous. An economy-or a company-can boost output in ways that are unsustainable, low-quality, or harmful. For example, a government might stimulate demand aggressively through debt-financed spending, temporarily lifting GDP without improving the underlying capacity of the economy to generate value. Similarly, a business can push employees to work longer hours, increase overtime, or underinvest in maintenance and training to hit short-term production targets.
These strategies may show up as rising output in quarterly reports, but they often erode long-term resilience and competitiveness. Overworked employees burn out, error rates climb, safety incidents increase, and turnover rises. Deferred maintenance can lead to costly breakdowns and lower reliability. Without investment in skills and technology, firms fall behind more efficient competitors. In macro terms, such patterns can contribute to economic cycles that look strong on the surface but are vulnerable to shocks.
There is also an environmental dimension. Output growth that depends on ever-greater resource extraction, energy consumption, and emissions can conflict with climate goals and long-term sustainability. Organizations such as the United Nations Environment Programme (unep.org) and the International Energy Agency (iea.org) stress that decoupling economic growth from environmental impact requires productivity improvements, especially in energy and resource use. Producing more with less-less carbon, less water, less waste-is a productivity challenge as much as a technological one.
From a strategic perspective, this is where the distinction between "working harder" and "working smarter" becomes critical. Firms and economies that prioritize productivity-through innovation, process improvement, and human capital development-are better positioned to achieve growth that is both economically and environmentally sustainable. This connection is increasingly visible in discussions around sustainable business models and green growth strategies.
How productivity shapes wages, jobs, and inequality
The relationship between productivity and wages has been at the center of economic debate for decades. In theory, in competitive markets, wages should track labor productivity over time because firms must pay workers roughly in line with the value they create. Historically, in many advanced economies, wage growth and productivity growth moved closely together through much of the 20th century.
However, research from organizations such as the Economic Policy Institute (epi.org) and the OECD indicates that since the 1980s or 1990s in several countries, especially the United States, median wage growth has lagged behind productivity growth. Several factors have been proposed: declining unionization, globalization, automation that substitutes for routine work, changes in labor market institutions, and rising market concentration in some sectors.
This divergence does not mean productivity no longer matters for wages. Rather, it suggests that the distribution of the gains from productivity growth has become more unequal. High-skill workers, capital owners, and firms with strong market power have captured a larger share of the benefits, while many mid- and low-skill workers have seen more modest gains. The result has been rising income and wealth inequality in many advanced economies.
For employment, productivity growth presents a double-edged narrative. On the one hand, technological change and automation can displace certain jobs, especially routine tasks in manufacturing, clerical work, and some services. On the other hand, productivity gains can lower prices, stimulate demand, and free up resources for new industries and roles. Historical evidence compiled by the World Economic Forum (weforum.org) and academic researchers shows that, over long periods, technology has tended to create more jobs than it destroys, but the transition can be painful and uneven.
For policy and business strategy, the implication is that productivity growth must be complemented by measures to support inclusive outcomes: skills development, active labor market policies, fair wage practices, and competition policy that limits excessive concentration. Without these, productivity improvements can coexist with stagnant wages for many, fuelling social and political tensions even as aggregate output grows.
From a practical career perspective, individuals who understand where productivity-enhancing technologies are heading-artificial intelligence, automation, data analytics-can better position themselves for roles that complement these tools rather than compete directly with them. This is one reason why coverage of AI and technology in the workplace has become central to discussions about jobs and productivity.
The productivity puzzle: technology without visible gains
One of the most discussed economic puzzles of the past decade has been the apparent disconnect between rapid technological progress-especially in digital technologies and AI-and relatively sluggish productivity growth in many advanced economies. Analysts from institutions like The Conference Board (conference-board.org) and central banks have documented that productivity growth slowed markedly after the mid-2000s, despite the widespread adoption of smartphones, cloud computing, and advanced software.
Several explanations have been proposed. One is measurement: traditional statistics may undercount the value of digital goods and services, many of which are free or low-cost to users but generate significant consumer surplus. Another is diffusion: frontier firms may be achieving strong productivity gains, but the majority of firms, especially small and medium-sized enterprises, lag behind in adopting and effectively using new technologies.
A third explanation is that reaping productivity benefits from technologies like AI and automation requires complementary investments in skills, organizational change, and process redesign. Simply installing new software or robots does not automatically translate into higher output per hour; firms need to rethink workflows, decision-making structures, and business models. This "implementation lag" can mean that the productivity payoff from major technological waves arrives years or even decades after the initial breakthroughs.
Recent advances in generative AI, including large language models and multimodal systems, have revived hopes that a new productivity surge may be emerging. Early studies by organizations such as MIT (mit.edu) and major consulting firms suggest significant potential time savings for certain knowledge tasks-coding, document drafting, customer support-especially for less experienced workers. But whether these gains will scale across entire economies depends on adoption, regulation, and organizational change. For business leaders and founders, the central question is how to integrate AI in ways that genuinely raise productivity rather than merely shifting tasks or creating new layers of digital bureaucracy.
For readers tracking these developments from a business or entrepreneurship perspective, this "productivity puzzle" sits squarely at the intersection of technology, founders and startups, and evolving world economic trends.
Why productivity matters for public finances, pensions, and social stability
Beyond firms and households, productivity growth is critical for the sustainability of public finances-especially in aging societies. As populations age, the ratio of working-age people to retirees falls. Without productivity gains, this means that either living standards must decline, taxes must rise sharply, or benefits must be cut to keep public debt under control.
Institutions such as the OECD, IMF, and national fiscal councils have repeatedly highlighted that higher productivity growth can ease these trade-offs. When each worker produces more, tax revenues per worker rise, making it easier to finance pensions, healthcare, and other age-related spending without unsustainable borrowing or large tax hikes. Conversely, if productivity remains weak, even modest increases in life expectancy and healthcare costs can put severe pressure on public budgets.
Productivity also interacts with social stability. In environments where productivity is rising and its gains are broadly shared, societies often find it easier to support social insurance, invest in education, and maintain political consensus around open markets and technological change. When productivity stalls and living standards stagnate for large segments of the population, support for economic openness and reform can erode. This has been visible in the rise of populist movements in several countries following prolonged periods of wage stagnation and perceived economic insecurity.
For policymakers, this makes productivity policy-education, innovation, infrastructure, competition, and regulatory frameworks-not just an economic agenda but a social and political one. For businesses, it underscores why engagement with skills development, fair employment practices, and community investment is increasingly seen not just as "corporate social responsibility" but as part of maintaining a stable operating environment.
How businesses can prioritize productivity over raw output
At the firm level, the difference between chasing output and pursuing productivity is often visible in management practices and investment choices. Companies focused narrowly on output targets may push for more hours, more units produced, or more sales volume without adequately considering margins, quality, or long-term capability building. By contrast, firms that prioritize productivity tend to invest in process improvement, technology, workforce skills, and data-driven decision-making.
Several levers are particularly important:
First, process redesign and lean management. Approaches inspired by lean manufacturing, Six Sigma, and agile methods focus on reducing waste, smoothing workflows, and empowering frontline teams to identify and solve problems. This can raise output per hour without overburdening staff and often improves quality and customer satisfaction at the same time.
Second, digital tools and automation. From robotic process automation in back-office functions to advanced analytics in supply chains, digital technologies can free employees from repetitive tasks and enable more value-adding work. However, as research from organizations such as Harvard Business School (hbs.edu) and INSEAD (insead.edu) emphasizes, technology investments pay off most when combined with changes in organizational structure, incentives, and skills.
Third, human capital and workplace design. Training, upskilling, and thoughtful job design are central to translating technology and process changes into productivity gains. Firms that invest in continuous learning, clear career paths, and supportive management practices often see higher engagement and lower turnover, both of which contribute to productivity. Flexible work arrangements and attention to well-being can also matter; burnout and disengagement are costly forms of hidden productivity loss.
Fourth, innovation and product strategy. Productivity is not only about internal efficiency; it also involves creating products and services that deliver more value per unit of input. This can mean moving up the value chain, embracing new business models, or leveraging data and platforms to create network effects. Startups and high-growth firms, in particular, often differentiate themselves by combining product innovation with scalable, high-productivity operating models.
For leaders, shifting the focus from output to productivity also means changing how performance is measured and rewarded. Metrics that emphasize value creation, quality, customer outcomes, and long-term capability building can encourage behaviors that support sustainable productivity growth. By contrast, incentives based purely on volume or short-term financial targets can push organizations into the trap of output-chasing at the expense of resilience.
Productivity, sustainability, and the next phase of global growth
The centrality of productivity growth is likely to become even more pronounced. Global demographic trends point to slower labor force growth in many major economies. At the same time, the imperative to reduce greenhouse gas emissions and environmental impact means that traditional models of growth based on expanding resource use are under increasing pressure.
This combination makes productivity-especially resource and energy productivity-a key lever for reconciling economic aspirations with planetary boundaries. Organizations such as the International Energy Agency, UNEP, and the World Bank highlight that achieving climate goals while supporting development in lower-income countries will require large improvements in how efficiently energy, materials, and land are used. Innovation in clean technologies, circular business models, and low-carbon infrastructure all contribute to this form of productivity.
For businesses, this creates both risks and opportunities. Firms that cling to resource-intensive, low-productivity models may face rising costs, regulatory constraints, and reputational challenges. Those that invest in energy efficiency, process innovation, and sustainable product design can often reduce costs and open new markets. For investors and analysts tracking markets and sustainable strategies, metrics that capture these dimensions of productivity are becoming increasingly important in evaluating long-term value.
In parallel, the rise of AI and digital platforms offers powerful tools to boost productivity in knowledge work, services, and public administration. But the outcomes will depend heavily on governance, skills, and institutional capacity. Countries and firms that combine technological adoption with strong education systems, adaptive regulation, and inclusive labor market policies are likely to see more of the benefits and fewer of the downsides.
For entrepreneurs and business leaders, the strategic question is less about whether to pursue productivity and more about how to embed it in organizational culture and decision-making. For workers and jobseekers, understanding where productivity-enhancing changes are happening-and developing skills that complement them-will be central to navigating careers in a shifting labor market. Those themes intersect closely with ongoing reporting around jobs and careers, technology, and business strategy.
Bringing it together: beyond bigger, toward better
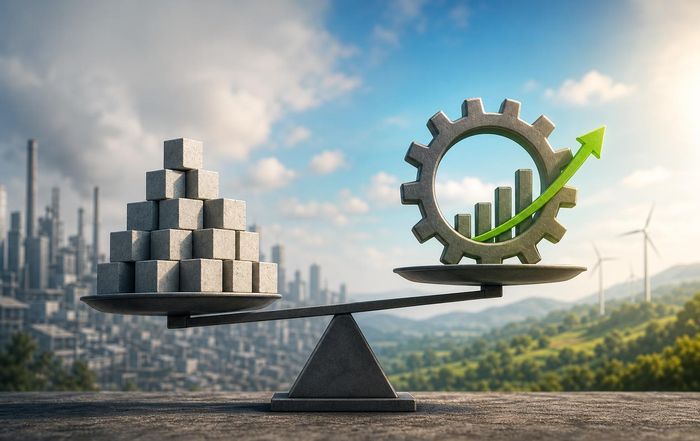
Output growth still matters. Economies and businesses need to expand to create opportunities, fund innovation, and meet rising aspirations. But when output becomes the sole or primary focus, it can mask underlying weaknesses: overreliance on long hours, underinvestment in skills and technology, environmental strain, and fragile public finances. Productivity growth, by contrast, is about improving the underlying engine-raising the amount of value created for each unit of labor, capital, and resources.
For policymakers, this means prioritizing education, infrastructure, competition, innovation ecosystems, and regulatory frameworks that support experimentation and diffusion of best practices. For businesses, it means investing in people, processes, and technology in ways that enhance efficiency and resilience rather than simply pushing for more volume. For workers, it underscores the importance of adaptability, continuous learning, and aligning skills with emerging productivity-enhancing technologies.
Ultimately, societies that focus on productivity growth-broadly shared and environmentally sustainable-are better placed to deliver rising living standards, fiscal stability, and social cohesion over the long term. Output figures may dominate the headlines, but it is productivity that quietly determines how far those numbers can go, and how much they truly improve people's lives.